Where an employer provides residential accommodation to an employee, or pays the rental on a property occupied by that employee, the arrangement can give rise to a taxable fringe benefit. An important distinction under South African tax legislation is that the taxable value of the accommodation is not necessarily equal to the rental paid by the employer.
In certain circumstances, an employer may pay R30,000, R40,000 or even R50,000 per month for an employee’s accommodation, while the taxable fringe benefit calculated under the prescribed statutory formula is considerably lower.
This creates legitimate remuneration-planning opportunities, particularly for employers recruiting senior employees, relocating staff or providing accommodation as part of an employment package. However, the correct treatment depends on the nature of the accommodation arrangement, the employee’s remuneration, the terms of the lease and the specific provisions of the Seventh Schedule to the Income Tax Act.
Legislative framework
The taxation of employer-provided residential accommodation is principally governed by:
- Paragraph 2(d) of the Seventh Schedule, which establishes the taxable benefit.
- Paragraph 9, which determines the cash equivalent of that benefit.
- The Fourth Schedule, which governs the withholding of employees’ tax (PAYE).
Under paragraph 9, the rental value is generally determined using the following formula:

The variables are:
| Variable | Description |
| A | Employee’s annual remuneration proxy, generally based on the preceding tax year |
| B | Statutory abatement of R99,000 for the 2027 tax year, subject to exclusions |
| C | Percentage of 17%, 18% or 19%, depending on the accommodation and facilities |
| D | Number of full months of occupation during the tax year |
How is the applicable percentage determined?
The percentage depends on the number of rooms and whether the employer provides furniture and power or fuel.
| Accommodation provided | Percentage |
| Fewer than four rooms, regardless of furniture or utilities | 17% |
| Four or more rooms, unfurnished, without power or fuel | 17% |
| Four or more rooms, either furnished or with power or fuel supplied | 18% |
| Four or more rooms, furnished and with power or fuel supplied | 19% |
The four-room requirement does not mean four bedrooms. Living rooms, dining rooms and bedrooms may count towards the threshold.
Practical example
An employee with an annual remuneration proxy of R1.2 million is provided with accommodation costing the employer R35,000 per month. After applying the R99,000 statutory abatement, the monthly taxable fringe benefit would be:
| Applicable percentage | Monthly taxable benefit |
| 17% | R15,597.50 |
| 18% | R16,515.00 |
| 19% | R17,432.50 |
Even at 19%, the taxable benefit is substantially lower than the R35,000 monthly rental paid by the employer.
Important considerations:
- The R99,000 abatement is not available in certain circumstances, including where the employee or their spouse controls the private company providing the accommodation.
- Where the employer leases accommodation from an independent landlord under an arm’s-length arrangement, and the statutory requirements are met, the taxable rental value is generally limited to the lower of the calculated amount and the employer’s actual accommodation expenditure.
- Qualifying rental contributions made by the employee reduce the taxable fringe benefit.
The result is that the rental expense incurred by the employer can be significantly higher than the taxable benefit attributed to the employee, creating potential tax efficiencies when accommodation is properly structured as part of an employment package.
Practical examples
The following examples assume that the employer leases the property directly from an independent landlord, the employee has no ownership interest in the property, accommodation is provided for 12 months, the 17% factor applies and the employee makes no contribution. All amounts in South African rand. Remuneration figures represent the applicable annual remuneration proxy.
| Scenario | Annual remuneration | Monthly rent paid by employer | Monthly taxable benefit | |
| 1. Junior employee | R360,000 | R15,000 | R3,698 | |
| 2. Mid-level employee | R600,000 | R25,000 | R7,098 | |
| 3. Senior employee | R1,200,000 | R35,000 | R15,598 | |
| 4. Executive employee | R2,000,000 | R45,000 | R26,931 | |
| 5. Rental below formula | R1,500,000 | R12,000 | R12,000 | |
For example, in scenario 3:
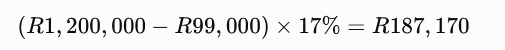
The annual taxable benefit is R187,170, or R15,597.50 per month, even though the employer pays R35,000 per month in rent. The difference of R19,402.50 per month is not included in the employee’s taxable remuneration merely because the employer incurs that additional rental expenditure. This is a valuation consequence of the legislation, rather than a separate tax exemption.
Why the contractual arrangement matters
The favourable treatment described above does not automatically apply whenever a company pays an employee’s rent. There is an important distinction between the employer providing accommodation and the employer paying an employee’s personal rental obligation.
Arrangement A: Employer leases the property
The company enters into a lease agreement with an independent landlord and makes the accommodation available to the employee as part of their employment. In this arrangement, paragraph 9 of the Seventh Schedule would ordinarily apply, and the prescribed fringe benefit calculation can produce a taxable value substantially below the actual rent.
Arrangement B: Employee leases the property
The employee enters into a lease agreement personally and remains responsible for the rent. The employer then pays the employee a monthly housing allowance or reimburses the employee for rental expenditure. A cash housing allowance will ordinarily constitute remuneration and be taxable in full. Similarly, the employer’s settlement of an employee’s personal obligation may fall under the debt-payment fringe benefit provisions rather than the residential accommodation valuation rules.
The distinction is therefore not simply who makes the payment. The underlying legal obligations, contractual rights and commercial substance must be considered. For this reason, where accommodation is to form part of an employment package, it is preferable that the employer genuinely provides the accommodation under a properly documented arrangement.
6. Comparing a housing allowance with employer-provided accommodation
Consider an employee earning R1,200,000 annually, with an additional accommodation package costing the employer R35,000 per month.
Assume the employee is subject to a 45% marginal tax rate, solely for purposes of illustrating the tax difference.
| Description | Cash housing allowance | Employer-provided accommodation |
| Annual salary | R1,200,000 | R1,200,000 |
| Annual housing cost | R420,000 | R420,000 |
| Additional taxable remuneration | R420,000 | R187,170 |
| Illustrative tax at 45% | R189,000 | R84,227 |
| Annual tax difference | R104,773 |
The employer incurs the same R420,000 annual housing cost under both arrangements.
However, the employee’s additional taxable remuneration differs by R232,830, producing an illustrative annual income tax difference of approximately R104,773.
This example demonstrates the potential tax efficiency of properly structured employer-provided accommodation.
Special considerations and potential exclusions
The Seventh Schedule provides for certain exceptions and adjustments to the general rules governing employer-provided residential accommodation. The following circumstances require specific consideration:
- Where an employee or their spouse controls the company providing the accommodation, the statutory abatement of R99,000 may not apply. This can result in a higher taxable benefit. The shareholding structure and the relationship between the employee and the employer must therefore be considered when determining the appropriate rental value.
- Where an employer provides accommodation to an employee who is required to work away from their usual place of residence, the accommodation may qualify for a nil taxable value, provided the relevant statutory requirements are satisfied.
- Where an employee contributes towards the cost of the accommodation, the taxable benefit is generally reduced by the qualifying amount paid. The treatment of additional contributions towards utilities, furniture and related expenses must be considered separately, depending on the nature of the arrangement.
- Special provisions may apply where the accommodation is owned by the employee, a connected person, or where the employee has an interest in acquiring the property. These arrangements require separate consideration, as the ordinary valuation rules may not apply in the same manner as they would to accommodation leased from an independent third party.
Employer-provided residential accommodation can offer a tax-efficient alternative to a conventional housing allowance, provided the arrangement satisfies the requirements of the Seventh Schedule to the Income Tax Act.
While a cash housing allowance is generally fully taxable, accommodation provided directly by an employer is subject to specific valuation rules that may result in a taxable benefit substantially lower than the actual rental cost incurred by the employer.
The key distinction is that the cost of providing the accommodation does not necessarily determine its taxable value. Where properly structured and administered, employer-provided accommodation can therefore offer meaningful tax advantages while preserving the full economic benefit to the employee.